-
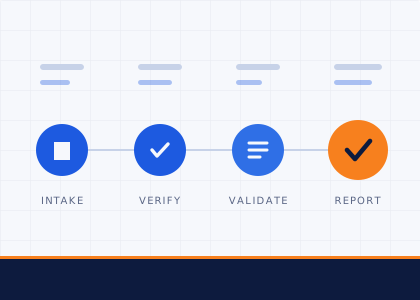
Data entry complete Address, employer and income filled from the sanction letter
-
2 calls logged Applicant confirmed. Reference rang out, retried next morning
-
Residence visited · 41 min on site Met the applicant. Nameplate matches. Neighbour vouched
-
Office verified Employer premises confirmed against the office library
-
Reviewed and signed Report released to the branch
Every address, actually visited.
Lenders send us a name, an ID and a sanction file. We send back a signed report with the photographs, the person who opened the door, and the hour it happened. No desk verification dressed up as field work.
One file, five stages
Nobody dispatches
anything by hand.
A file arrives and starts moving on its own. Work lands on whoever is carrying the lightest queue, and the next stage opens the moment the last one closes.
Collected
The sanction file is picked up at the branch and the applicant, reference and branch are posted into the queue.
Assigned
The job routes to the executive carrying the fewest live files. They are notified in the same second.
AUTOMATICCalled
Every dial is logged with who answered, what they said, and what did not add up.
Visited
Residence and office trips schedule themselves. Photographs are geo-stamped as they are taken.
AUTOMATICStamped
A reviewer signs the verdict and the report lands in the branch manager's inbox.
About the company
The operational arm behind the credit decision.
Jay Ess Unity India Private Limited is a business-support services company in Hosur, Tamil Nadu, providing outsourced verification and operational support to financial institutions. Behind the company sits more than fifteen years of hands-on experience in loan processing, field verification and background checks. Our teams work as an extension of the lender's own operations, gathering the information credit teams need during the loan-processing lifecycle.
We don't make the lending decision. We make sure the information behind it holds up — collected through a defined process, checked before release, and reported in the format each client asks for.
See what the branch receives
Accuracy first
Every verification runs against defined guidelines, not judgement calls made at the gate.
Turnaround discipline
Allocation, tracking and escalation exist to keep cases inside the agreed TAT.
Process driven
Standard workflows keep findings consistent across executives, cities and case volumes.
Confidential by default
Customer and financial data is handled under controlled access and client-defined rules.
What we do
Verification services,
built around your process.
Every engagement runs on the verification parameters, documentation formats and service levels the lending institution defines. Open a service to see what a typical scope covers.
S/01 Customer & applicant verification
Structured verification of the applicant's declared information — who they are, where they live, where they work, and whether the profile submitted with the loan application holds up when someone checks it in person.
S/02 Field investigation
On-ground investigation by trained field executives. They reach the location, observe conditions against the parameters you set, record what they find and report it without interpretation. Photographs are geo-stamped as they are taken.
S/03 Document verification support
Validation support for the documents submitted with a loan application — checking that what has been declared matches what has been supplied, and flagging the gaps back to the credit team rather than quietly closing over them.
S/04 Tele verification
Structured telephone verification run to your own script and disposition codes. Every dial is logged — including the ones nobody picked up — so the credit officer sees the attempts, not just the outcomes.
S/05 Property verification support
Field-level property checks for housing and secured lending. The executive reaches the site, confirms the address exists as described, records occupancy and condition, and photographs each elevation with a geo-stamp.
S/06 Loan processing support
Operational support across selected stages of the lending workflow — intake through verification, validation and reporting — so your internal team spends its time on credit decisions rather than coordination.
The clever part
The trip that didn't happen.
Six applicants from the same employer means six photographs of the same lobby. So we keep a library of offices we have already verified. When a file names one of them, that visit closes itself — and nobody drives across the city to photograph a reception desk twice.
TRY IT — PICK AN EMPLOYER
Residence visit
ScheduledOffice visit
Closed instantlyFive desks
Everyone sees exactly
their own work.
A tele-verification agent opens the app and finds their files. A field executive finds addresses and a camera. Nobody scrolls past work that isn't theirs, and nobody sees a customer record they have no reason to hold.
Admin
The whole board — queue, people, branches and turnaround analytics.
Data feeder
Walks into the branch, walks out with the file, posts it into the queue.
Agent
Fills the missing fields, makes the calls, logs every word of them.
Field executive
Directions, camera and the observation sheet. Built to work one-handed.
Reviewer
Reads the file, sets the verdict, signs it and sends it to the branch.
What the branch receives
A document a credit officer can act on.
Not a spreadsheet row. A letterheaded report with the photographs inline, every call in a table, and one verdict at the top that says what to do next.
- Your letterhead, signature block and footer
- Photographs inlined per visit, captioned and geo-stamped
- Every call attempt, including the ones nobody picked up
- Reused office photographs labelled as reused — never passed off as fresh
- Reference
- JEU/26/HSR/04812
- Applicant
- R. Priyadarshini
- Raised by
- Housing finance partner — branch code masked
- Residence
- Confirmed · owned · 6 yrs
- Office
- Verified
- Turnaround
- 27 hours
Why Jay Ess Unity
Reliable verification.
Better operational efficiency.
Lenders don't change verification partners for marketing. They change for turnaround, report quality and fewer cases coming back for rework.
Experienced operations
Our teams know where verification sits in the lending lifecycle, and what a credit officer actually needs out of the report.
Scalable location coverage
Field and tele capacity built to extend to the locations and pin codes your portfolio actually lends into.
Faster turnaround
Auto-allocation to the lightest queue removes the dead time between a case being raised and someone reaching the door.
Structured reporting
Clear, standard reports your credit team can act on immediately, in the format and fields you specify.
Process compliance
We follow your verification parameters, documentation requirements and service levels — not a generic in-house template.
Professional field teams
Executives trained on customer interaction, documentation and confidentiality. They represent your brand at the applicant's door.
The ground beneath the decision
Lending runs on information
somebody stood next to.
Sanction files move fast. What slows them down is a verification result nobody can vouch for. We put a person at the address, log what they found, and sign it.
Who we serve
Built for the lending ecosystem.
We work with institutions where a verification result feeds straight into a credit decision — retail lending, home loans, and secured and unsecured portfolios.
Banks
Verification support across retail and business lending portfolios.
Housing finance companies
Applicant, residence and property field verification for home loans.
NBFCs
Scalable field investigation and verification support at volume.
Other financial institutions
Customer, address, employment, business and property verification on request.
In their words
What partners say about
working with us.
Quality & confidentiality
Sensitive information, handled the way it should be.
Loan verification means holding customer and financial data. Access is scoped to the desk that needs it, communication is controlled, and handling follows the compliance requirements each client sets out in the engagement.
- Data confidentiality
- Role-scoped access
- Controlled handling
- Secure communication
- Quality checks before release
- Client-defined compliance
Coverage
Field capacity that follows your portfolio.
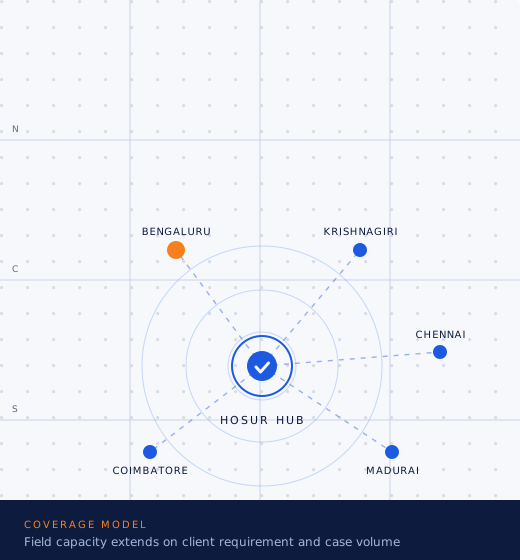
We operate from Hosur with a desk in Bengaluru, and extend field coverage on client requirement and case volume. Share the pin codes you lend into and we'll confirm what we service today.
A lending decision is only as reliable as the information behind it.
We don't approve or reject applications. Our job is to put accurate, timely, ground-level information in front of the people who do — inside the turnaround your process depends on.
Common questions
Before you send the first case.
What exactly does Jay Ess Unity verify?
Applicant profiles, residential and office addresses, employment, business premises, references, submitted documents and property sites. Each engagement is scoped to the verification types you actually need.
Do you follow our verification format or your own?
Yours. We work to the verification parameters, report fields, documentation requirements and service levels defined by the lending institution. Our internal process governs how the work gets done, not what gets asked.
What is the office library, and why does it matter?
It's a record of employer premises we have already visited and photographed. When a new file names one of them, the office visit can close against the existing record instead of sending someone to photograph the same reception desk again. Every reused photograph is labelled as reused, so a reviewer always knows what is fresh and what is on file.
What turnaround can we expect?
TAT is agreed per engagement and depends on verification type, location and volume. Cases are allocated automatically and monitored against the agreed TAT while they are live, rather than reported on after the fact.
Which locations can you cover?
We operate from Hosur, Tamil Nadu, and extend field coverage based on client requirement and case volume. Share the pin codes your portfolio lends into and we'll confirm what we can service today and where we would need to build.
How is customer data handled?
Access is scoped by desk, so a field executive sees an address and a camera while a reviewer sees the file. Handling, retention and communication follow the compliance requirements set out in the client agreement.
Can you handle volume increases?
The operating model is designed to scale case volumes up and down against demand. Give us your expected monthly case count and seasonal peaks and we'll map the field capacity required.
Contact
Send us the file.
We'll send back the doorstep.
Tell us your verification types, service locations and expected case volumes. We'll come back with coverage, turnaround and a working model.
No 3 & 4, 1st Floor, Outer Ring Road,
Behind RC Church, Hosur,
Krishnagiri, Tamil Nadu 635109